
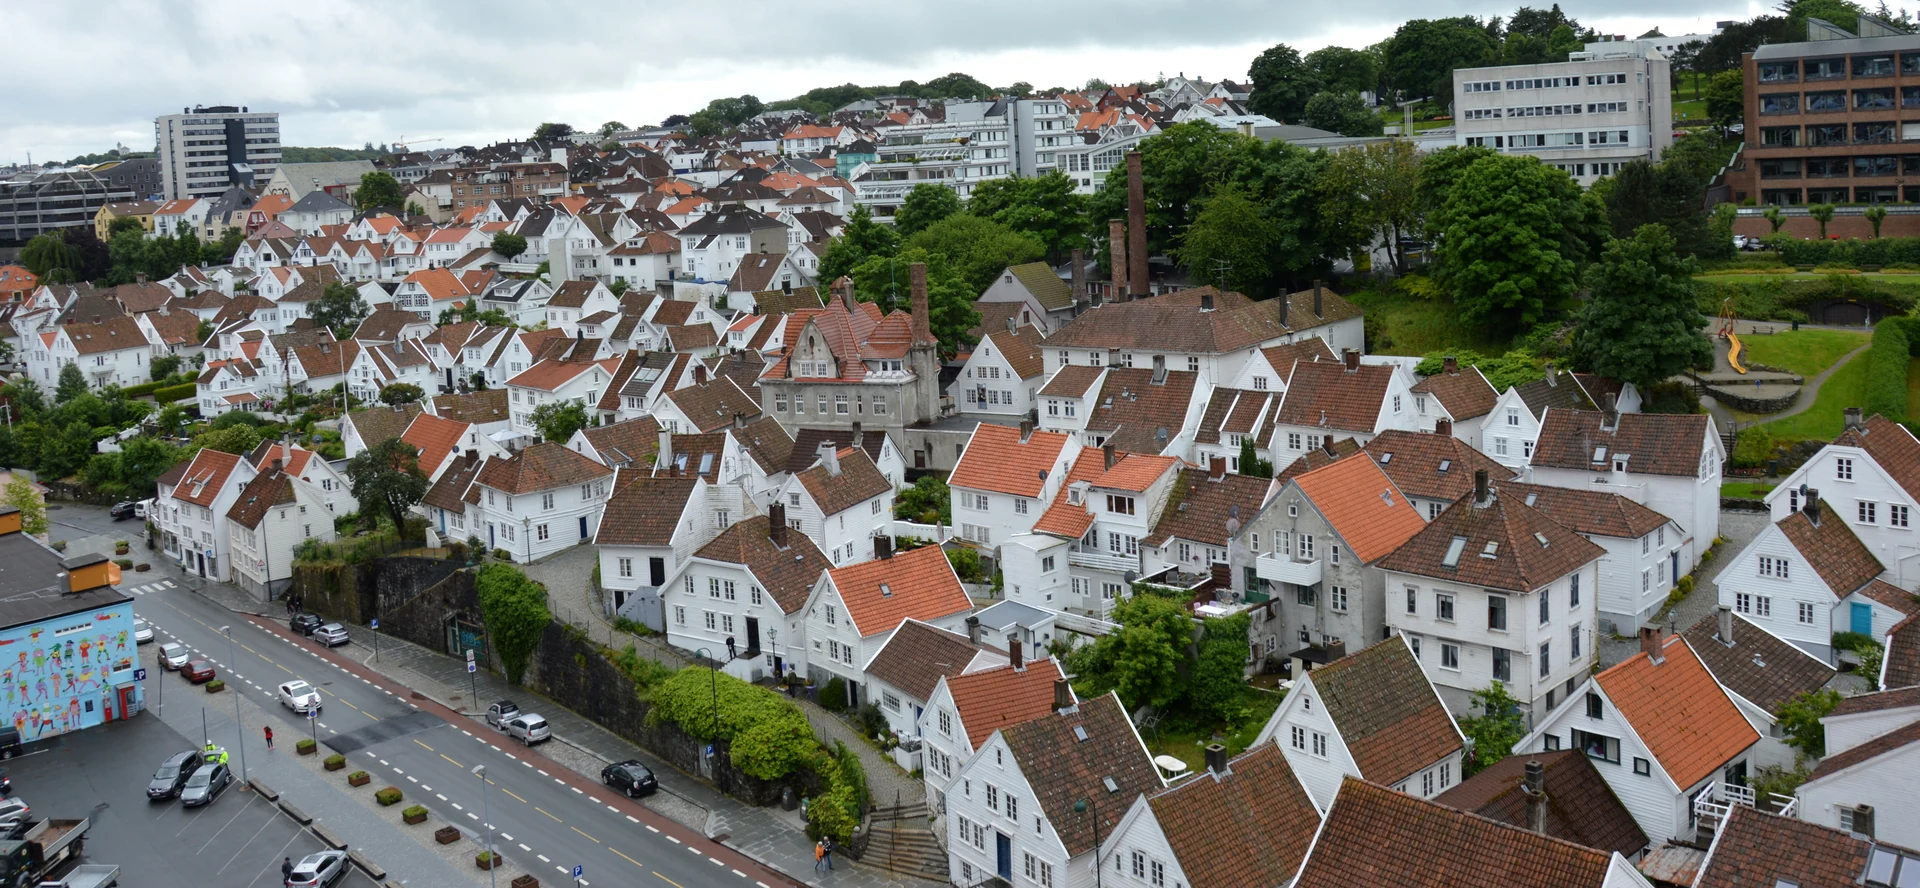
A real operating and living decision
Norway is worth considering as a place to build a household or operate a business, but a relocation needs more than an attractive city and a registered entity. Resident worldwide income taxation, annual wealth tax and a substantive departure regime can materially affect a founder’s plan. Immigration permission and tax residence answer different questions.
The practical starting point is your existing structure: where you live, what you own, where the team works and what you want to change. Establishing a Norwegian operation while retaining an international group requires a different analysis from moving a portfolio-owning household or leaving an established Norwegian company behind.
Find the decision you need to resolve
| Item | How it works | Planning consequence |
|---|---|---|
| Moving your household | Permission, residence start date, wealth and company work | Use the relocation and personal-tax guides together. |
| Operating a business | Entity residence, NOKUS, VAT, payroll and banking | Build the operating model before selecting the entity. |
| Moving away | Domestic cessation, treaty residence and exit calculations | Model the change before the triggering event. |
| Long-term settlement | Renewable permission, permanent residence and nationality | Each stage has independent requirements. |
The country and the practical base
Norway uses the Norwegian krone, so a household earning in another currency should budget for conversion and currency risk. Statistics Norway reported 5,636,904 residents at the end of June 2026. National population is context, not a proxy for a city’s housing availability.
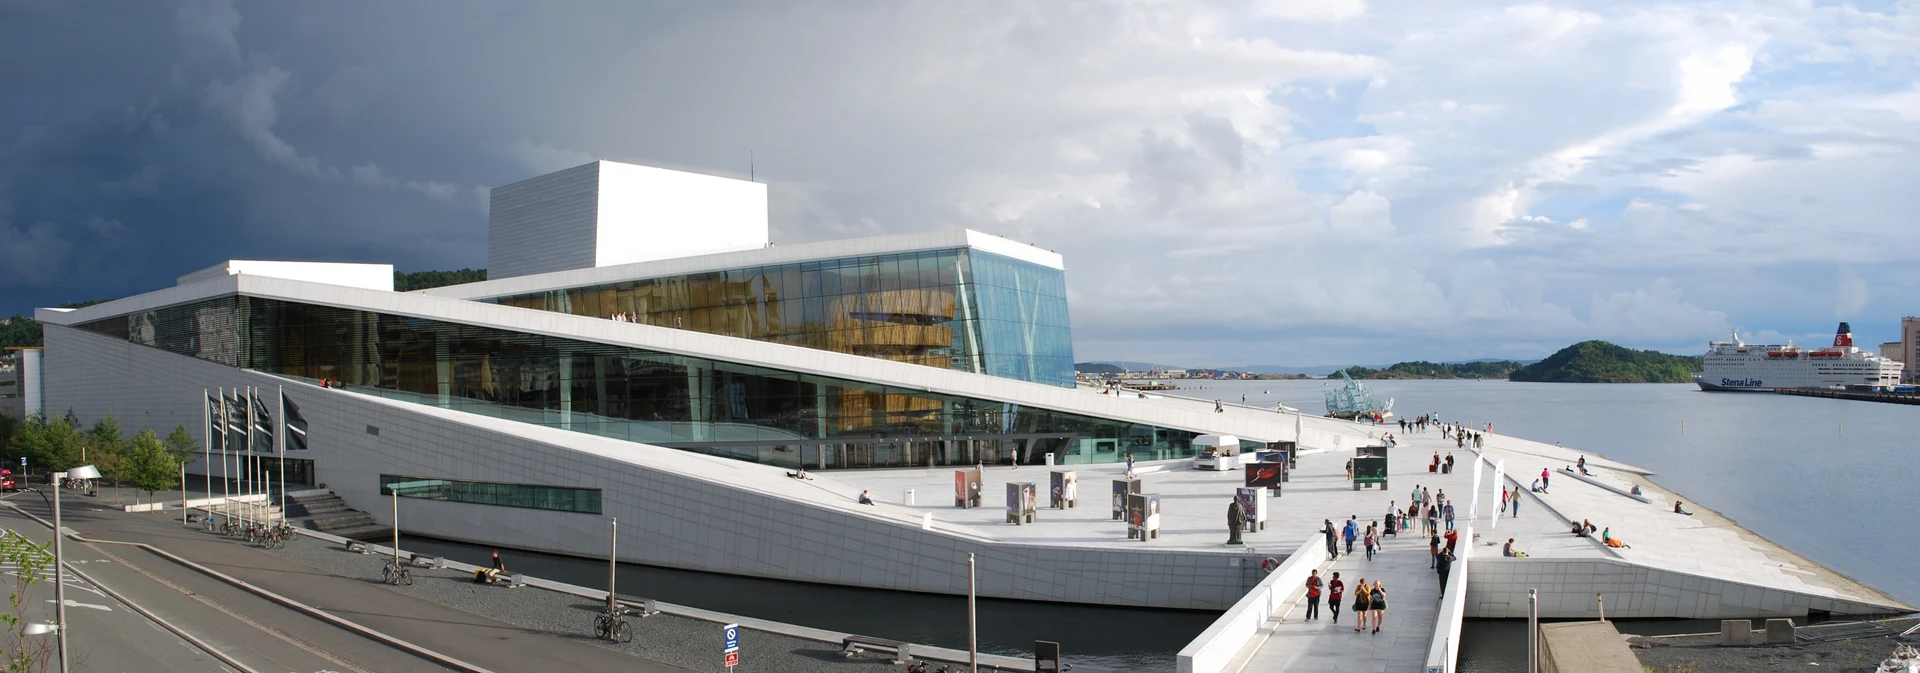
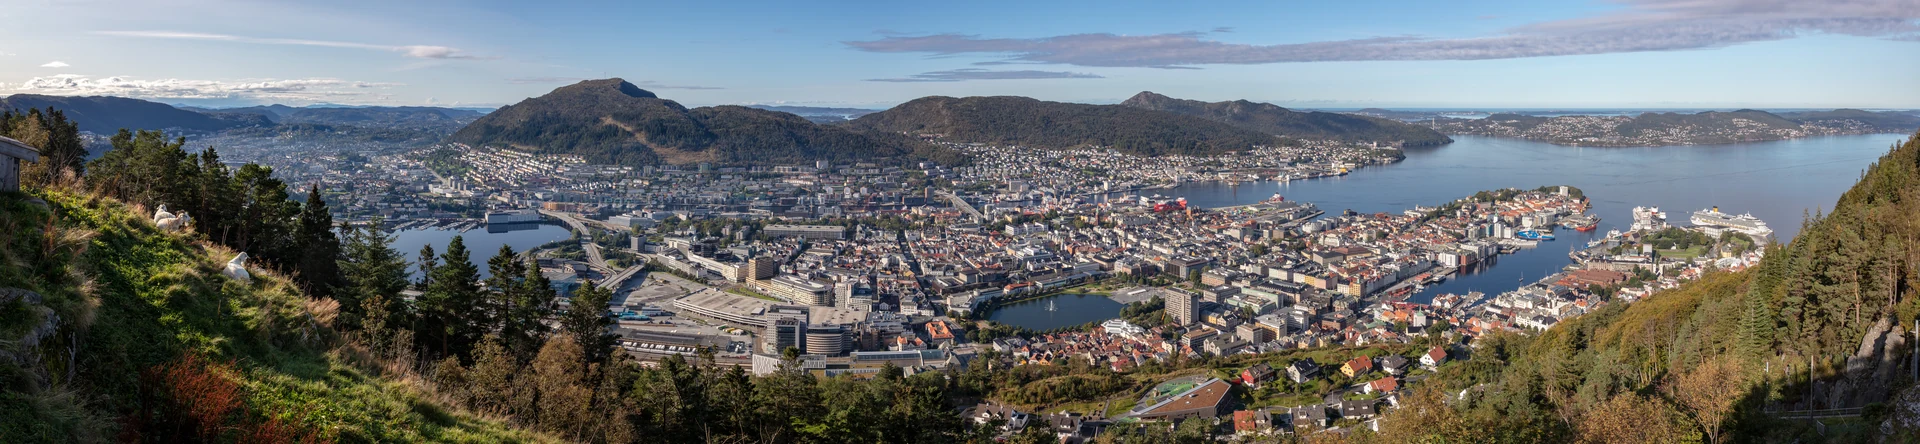
Regional climate and daylight differ substantially. An Oslo apartment, a western coastal home and a northern location should not be assessed using one national weather description. Visit in a season that tests the intended lifestyle, including the ordinary school and work routine.
Start with your nationality and intended activity
EU/EEA residence rights and third-country permits follow different processes. Norway participates in the EEA; this should not be presented as Norwegian EU membership. A third-country entrepreneur should not assume that acquiring a company creates permission to work in it.
The specific self-employed route researched here ordinarily concerns an active skilled sole proprietor. It is not a passive investment programme or a limited-company ownership shortcut. The residency guide separates that route from employment, family and EEA options.
Bring the whole structure into the first review
Useful preparation includes an ownership chart, recent accounts, a list of assets and unrealised gains, travel history, family nationalities and a summary of the work that would be done in Norway. Identify the decisions that cannot easily be reversed: selling or transferring shares, changing treaty residence, signing a long lease or moving key management.
Offshore Capitalist can discuss how the personal and business questions fit together and scope the analysis and implementation support that is appropriate. The work should establish a documented plan, the local specialists needed and the steps for keeping it compliant after the move.
Sources & research notes10 references
Sources supporting this guide. Research draft awaiting editorial review.
- Skatteetaten — worldwide tax liability
- Skatteetaten — wealth-tax rates
- Skatteetaten — current individual exit tax
- Skatteetaten — tax liability of foreign businesses
- UDI — skilled workers, self-employed in Norway
- Norges Bank — legal-tender notes and coins
- Statistics Norway — population, Q2 2026
- Meteorological Institute — weather and climate
- UDI — self-employed EU/EEA nationals
- UDI — skilled-worker and sole-proprietor questions