Special tax programmes
Personal and business regimes, eligibility tests and limits.
Uruguay’s 2026 new-resident tax regime
 Uruguay
A conditional foreign-capital-income election with annual evidence and later alternatives.
UAE qualifying free-zone income
 United Arab Emirates
Understand when the conditional 0% corporate-tax treatment can apply, and why a free-zone licence alone is insufficient.
New Zealand transitional-resident exemption
 New Zealand
Temporary relief for many foreign-income categories, with a precise eligibility history and important employment exclusions.
Italy new-resident tax regime: eligibility, foreign income and election
 Italy
A defined election for eligible foreign income, with higher amounts for qualifying new arrivals from 2026.
Portugal IFICI tax incentive: qualifying activities and registration
 Portugal
A targeted incentive for qualifying research, innovation and other specified activities—not a blanket tax status for new residents.
Spain impatriate tax regime: Article 93 eligibility and election
 Spain
The regime commonly called Beckham law is an eligibility-based election with defined income and timing rules.
Cyprus non-dom tax status and the 60-day residence rule
 Cyprus
A residence-and-domicile analysis, not a flat exemption for every kind of income.
Malta Global Residence Programme: remittances, tax and conditions
 Malta
A special tax-status route for eligible third-country individuals, distinct from Malta permanent residence.
Greece Article 5A tax regime: investment, annual charge and application
 Greece
A foreign-income election for qualifying arrivals, with an investment condition and continuing payment obligations.
UK four-year foreign income and gains regime: eligibility and claims
 United Kingdom
A limited arrival window for eligible foreign income and gains, requiring an active claim and careful planning beyond year four.
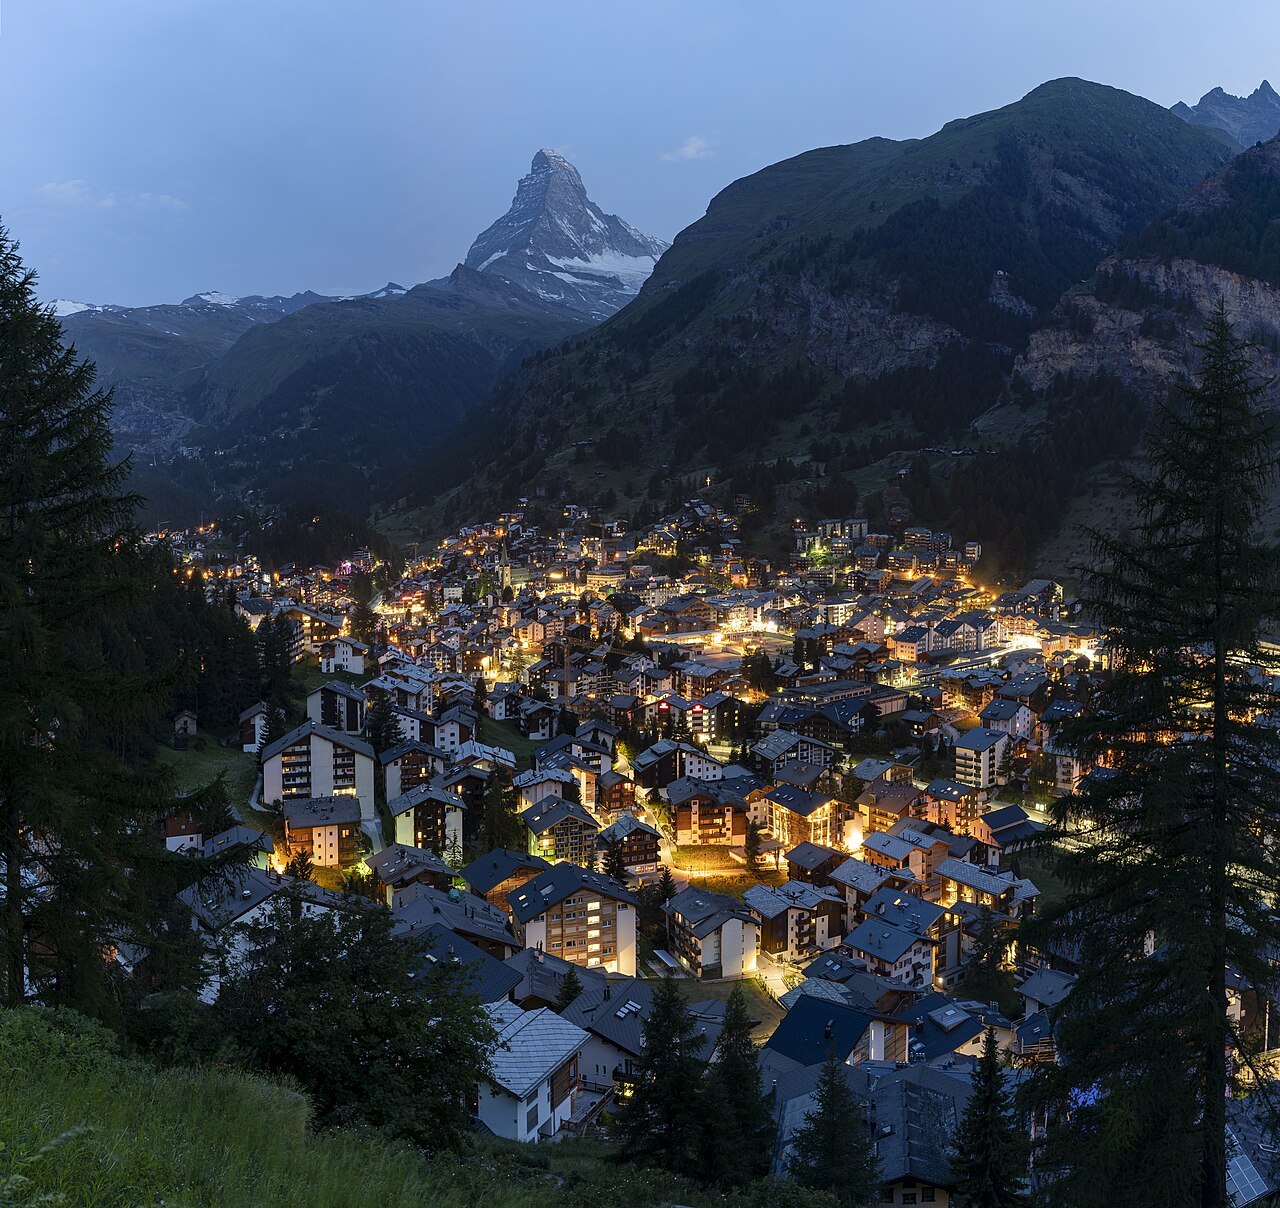
Swiss expenditure-based taxation: eligibility and cantonal process
 Switzerland
A canton-specific tax framework for qualifying individuals, requiring a separate immigration decision.
Türkiye’s 20-year foreign-income exemption
Who can qualify under article 20/D, when to apply, and why the source of income still matters.