
Choose the life and the permission together
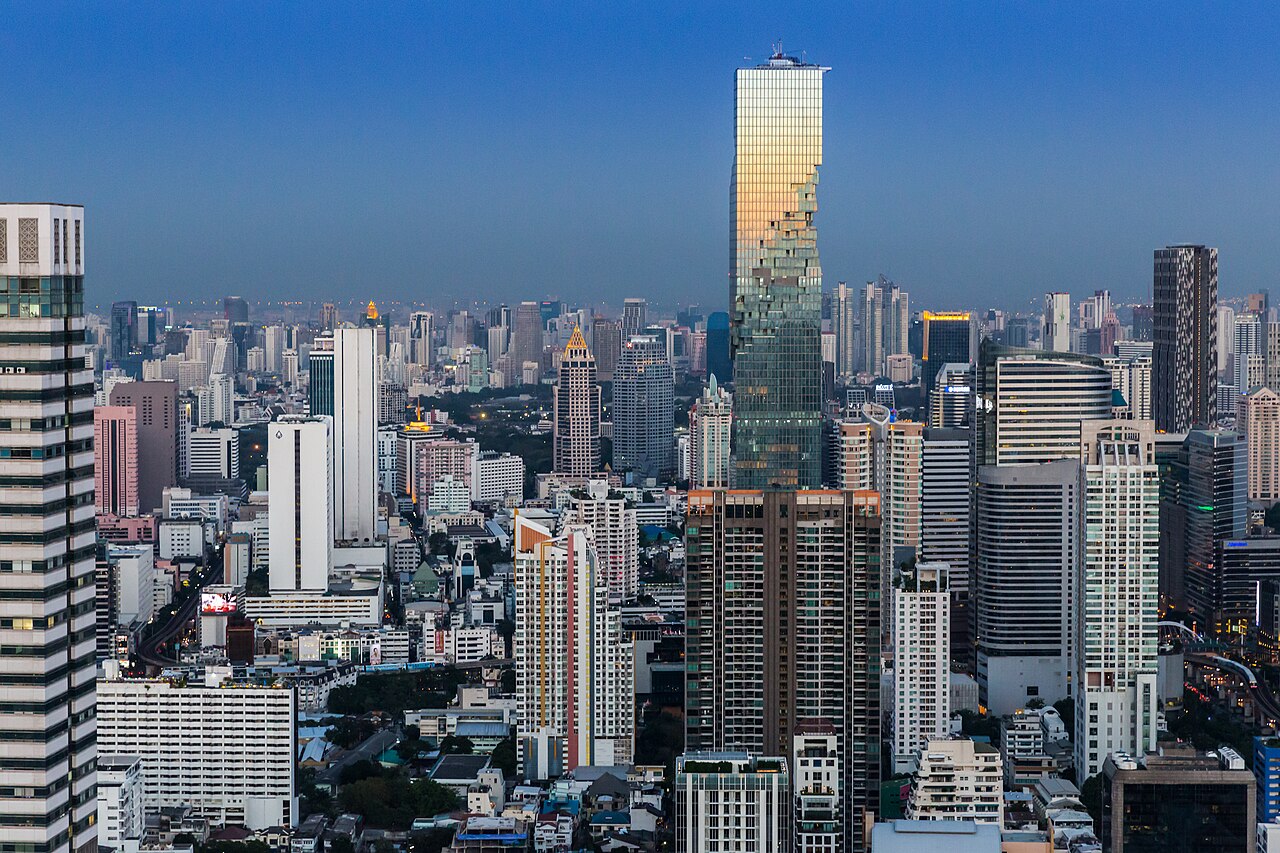
Thailand offers urban business environments, established expatriate communities and very different regional lifestyles. The relevant residence route depends on whether you will work remotely, hold qualifying employment, retire or make an investment. Long duration on a visa does not make those activities interchangeable.
Three popular routes serve different purposes
DTV addresses qualifying remote work and specified activities. LTR is a qualification-based programme with distinct categories and continuing conditions. Thailand Privilege is a paid membership and long-stay facility. None should be marketed as a universal exemption from Thai income tax. A person can be legally admitted and still need a separate tax and employer review.
Prepare for the remittance question
The Revenue Department’s guidance for foreign-source income from 2024 connects taxation to residence in the year income arises and its later remittance. Historic savings, current earnings and transfers between accounts should be distinguishable. An organised record of funds is considerably more useful than guessing from the description on a bank transfer.
Choose between three very different long-stay propositions
DTV, LTR and Thailand Privilege solve different problems. DTV is relevant to qualifying remote workers, freelancers and specified activities, with documentary and financial requirements. LTR targets particular high-income, asset or professional categories and can include category-specific tax benefits. Privilege is a paid membership supporting a long-stay immigration facility. Paying for convenience does not create permission to perform every kind of work.
Compare the required documents with the actual facts. An overseas employee should be able to show the employer and remote role. A freelancer needs genuine professional evidence. A pensioner needs qualifying passive income for the relevant LTR route. A company owner working for their own foreign company must assess both the immigration category and the business consequences of managing it from Thailand. The most expensive route is not automatically the best fit.
The visa’s duration and each permitted stay are different clocks
DTV has five-year multiple-entry validity, but the ordinary permitted stay is 180 days per entry, with a possible 180-day extension under its conditions. A holder cannot read five-year validity as permission to remain continuously for five years. LTR uses a ten-year framework with a five-year qualification review, while Privilege benefits depend on the purchased package and immigration conditions.
Plan entry, extensions, reporting and renewals as separate calendar items. The responsible embassy’s jurisdiction and document list matter for an overseas application. A resident of one country should not assume that a neighbouring mission will accept their file simply because its fee is lower or an online comment says it is faster. Official processing targets generally start when the required file is complete.
The remittance analysis starts with when income was earned
The Revenue Department’s detailed foreign-income guidance distinguishes income arising before 2024 from income earned from 1 January 2024. For the latter, residence in the income year and later remittance are relevant. A foreign account can hold several different things: old savings, new wages, sale proceeds, investment cost and taxable gains. The account’s opening date does not determine the treatment of every later receipt.
Prepare a record of what each transfer represents and retain the underlying statements. Separate genuine foreign income from income connected to work performed in Thailand. A foreign employer or customer does not automatically make locally performed services foreign-source. Treaty treatment and foreign tax credits may help in an overlap, but require evidence and the correct income classification. Avoid planning around an announced proposal before verifying that operative legislation has changed.
Build the household and business plan together
A move should account for family permissions, school and healthcare arrangements, an adequate insurance policy and usable banking. LTR’s insurance or financial alternative is a programme condition; it is not a substitute for examining whether the family’s actual medical needs are covered. Capital committed to investments, evidence of savings and non-refundable membership or government fees belong on separate budget lines.
For a business owner, map the functions performed from Thailand and the people left abroad. A long-stay permission does not resolve corporate residence, permanent-establishment, local licensing or employer obligations. Keep contracts, board authority and work locations aligned with reality. Offshore Capitalist can coordinate the international assessment and implementation, while local regulated work and immigration decisions remain with the appropriate providers and authorities. The linked programme guides set out the specific application stages and evidence.
How Offshore Capitalist can help
Share your current residence, nationality, business activities and intended changes through the inquiry form or WhatsApp. We can assess the cross-border issues, explain the work required and coordinate the agreed implementation. For this jurisdiction, local regulated work and government decisions remain with the relevant qualified providers and authorities. We confirm scope and fees before starting.
Sources & research notes12 references
Sources supporting this guide. Research draft awaiting editorial review.
- Thai MFA: DTV framework
- BOI: Long-Term Resident visa
- Thailand Privilege: official membership packages
- Thai Revenue Department: foreign income rules from 2024
- Revenue Department: personal income tax
- BOI: 2025 LTR eligibility brochure
- Thailand Privilege: published membership comparison
- Royal Thai Embassy Copenhagen: DTV and jurisdiction conditions
- BOI Announcement Por 4/2568: LTR endorsement and extension process
- Royal Thai Embassy London: current visa processing and document requirements
- Revenue Department: Thai and foreign income sources
- Revenue Department: 2026 personal return and foreign-income forms