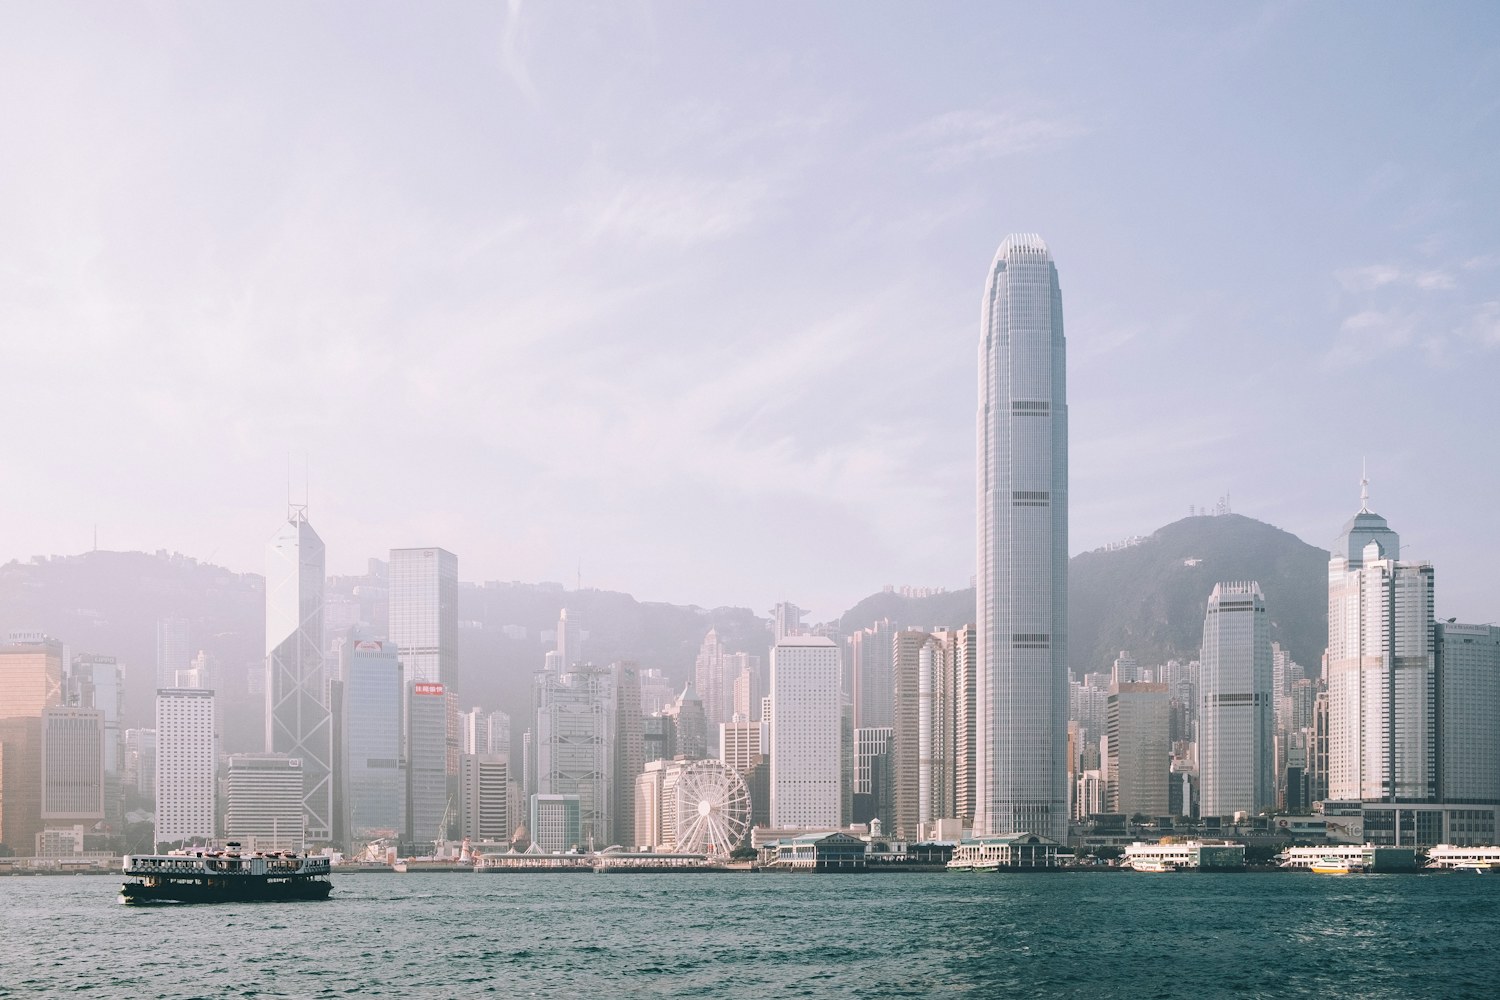

A commercial base, not a generic offshore label
Hong Kong combines international banking, company infrastructure and proximity to Asian supply chains. Its tax system is commonly described as territorial, but the location of a company registration or bank account does not determine where profits arise. An online business needs to examine its actual transactions and operations.
Residence has several meanings
Immigration permission allows a person to live or work under particular conditions. Ordinary residence and right of abode use different tests. Chinese nationality is another question again. A foreign resident who becomes a permanent resident after the required period does not automatically acquire eligibility for an HKSAR passport.
Look at the whole group
Multinational groups must consider the foreign-sourced income exemption regime. Certain foreign dividends, interest, intellectual-property income and disposal gains received in Hong Kong can be taxable unless conditions are met. This matters for holding companies as well as larger groups; the regime is not simply restricted to very large revenue businesses.
Start with the commercial connection to Hong Kong
Hong Kong can be useful for an entrepreneur dealing with Asian suppliers, international trading, regional customers or an investment business. But the case for a company should identify which functions belong there. Incorporation, banking, immigration and the source of profits are four separate assessments. An international bank account does not establish that profits are offshore, and a Hong Kong company does not automatically give its shareholder permission to live or work locally.
Map the business’s contracts and operations before choosing the structure. For an e-commerce group, distinguish product sourcing, inventory, marketing, customer contracts, platform accounts and management. For a service business, identify where the people performing the work sit. Those facts are more useful than the currency of the invoice or the location of the receiving bank. They also determine which foreign-country obligations remain after a Hong Kong entity is introduced.
Territorial profits tax requires evidence of profit-producing operations
The territorial source principle looks at what the taxpayer did to earn the profit and where those activities occurred. Different businesses need different evidence: a trading operation may require the contract-negotiation and execution trail, while a service business needs records of the work performed. An offshore claim is not a status purchased at incorporation. Changes in the operating model can change the result.
The two-tier corporate profits-tax rates are 8.25% on the first HK$2 million of assessable profits and 16.5% above that, where the regime applies. Connected entities cannot each assume access to the lower band. Separately, the foreign-sourced income regime can tax specified foreign receipts of MNE entities unless an exception applies. A holding company receiving dividends or selling a subsidiary therefore needs analysis beyond the usual trading-company source discussion.
Immigration should follow a credible business or personal route
An entrepreneur application considers the applicant’s contribution to Hong Kong, including business feasibility, funding, investment, jobs and relevant skills or technology. The Immigration Department asks for a three-year business plan and financial projections. There is no universal small incorporation payment that guarantees approval. The quality of the evidence and the actual business matter.
Employment, talent and investment-related routes have different criteria. Select the route that genuinely describes the applicant, then build the supporting file. Long-term plans should distinguish ordinary residence, permanent resident status and Chinese nationality. Seven years of qualifying ordinary residence can be relevant to permanent residence, but that is not a seven-year guarantee of a Hong Kong SAR passport. A non-Chinese permanent resident remains subject to separate nationality requirements.
Banking and ongoing administration are part of the decision
A useful account must support the real industry, counterparties, currencies and payment volume. Prepare the group ownership chart, business-registration records, contracts, invoices and evidence of initial funding. Banks may ask why a locally registered company has no visible Hong Kong operating connection; answer with facts rather than a generic description of international trade. A fintech payment account may solve a particular collection problem without providing every feature of a bank account.
After opening, maintain accounts, statutory filings, tax returns and current information about beneficial owners and signatories. Retain the evidence supporting any offshore-source position. If the owner later leaves Hong Kong, review employee tax clearance and where the company will be managed. Account approval and a favourable tax conclusion are both relationships with continuing conditions, not one-time certificates that remove future review.
How Offshore Capitalist can help
Share your current residence, nationality, business activities and intended changes through the inquiry form or WhatsApp. We can assess the cross-border issues, explain the work required and coordinate the agreed implementation. For this jurisdiction, local regulated work and government decisions remain with the relevant qualified providers and authorities. We confirm scope and fees before starting.
Sources & research notes8 references
Sources supporting this guide. Research draft awaiting editorial review.
- IRD: territorial source of profits
- IRD: foreign-sourced income exemption regime
- Hong Kong Immigration: right of abode
- Immigration Department: Chinese nationality
- HKMA: account opening and maintenance
- Hong Kong Immigration: investment as an entrepreneur
- IRD: two-tier profits tax and connected entities
- IRD: employer departure reporting and withholding