Banking in Canada
The banking system, major banks and digital alternatives, account-opening requirements, and what can be arranged remotely.
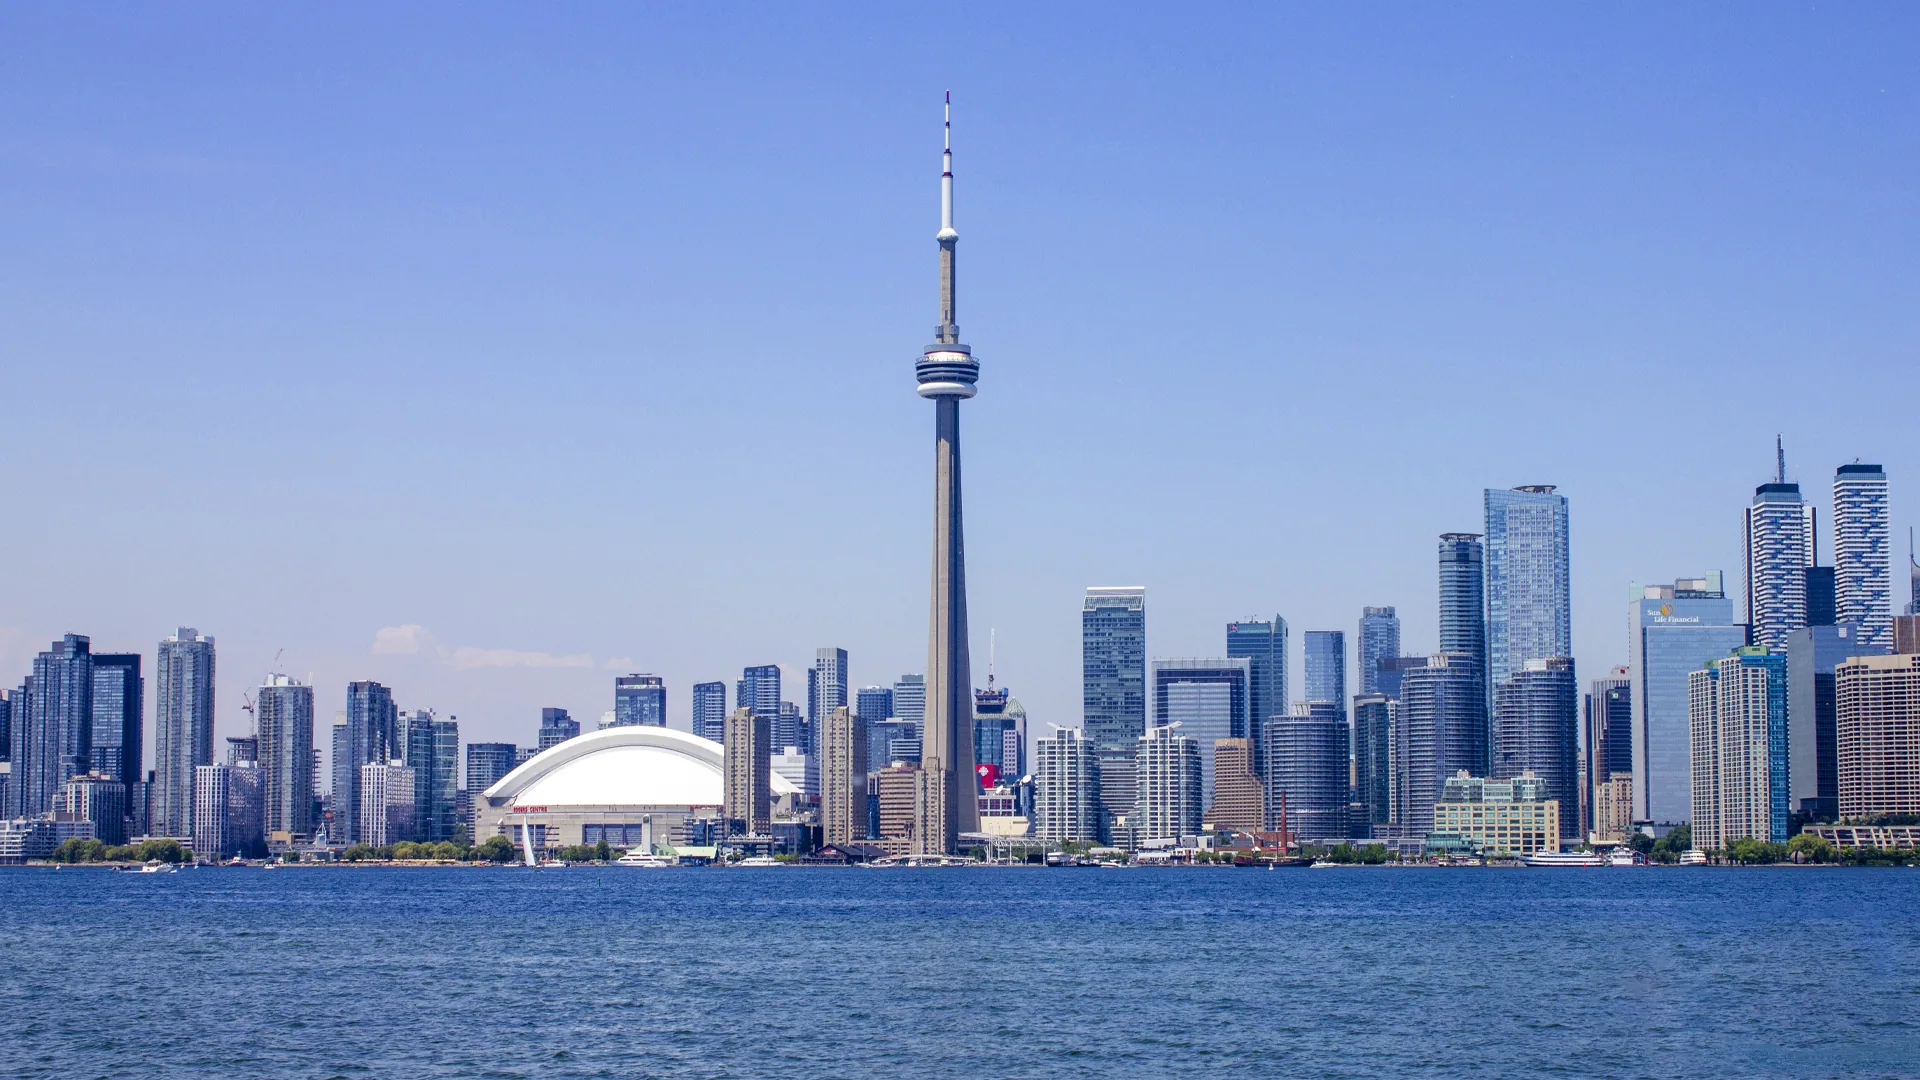
How the banking system works
Canada has large national banks, smaller banks and digital banking brands, alongside credit unions and Québec’s caisses populaires. The six major banks provide everyday accounts, business banking and investment services; digital providers often offer a narrower range.
Everyday money
A chequing account handles salary, bills, debit purchases and transfers. A savings account holds cash earning interest; a guaranteed investment certificate (GIC) locks money into specified terms.
Supervision
The Office of the Superintendent of Financial Institutions (OSFI) supervises federally regulated banks. The Financial Consumer Agency of Canada (FCAC) oversees federal consumer-protection rules.
Deposit protection
Canada Deposit Insurance Corporation (CDIC) protection covers eligible deposits up to CAD100,000 per insured category at each member institution, including interest.
Details & sources
CDIC covers eligible deposits, not losses on shares, mutual funds, exchange-traded funds or crypto. Multiple brands can belong to the same member institution: check the legal issuer before assuming separate coverage.
Provincially regulated credit unions and caisses can have different deposit insurers and limits. An investment dealer’s protection is separate from deposit insurance and does not insure market returns.
Banks & everyday banking providers
A starting directory of major consumer-facing institutions and brands. Use the official registers below for the full regulated-bank and deposit-insurance membership lists.
| Bank / provider | Type | Services | Access |
|---|---|---|---|
 Royal Bank of Canada (RBC) | Major bank | Personal and business banking, investments, and cross-border banking services. | Branch network; online applications for eligible accounts. |
 TD Canada Trust | Major bank | Everyday and business accounts, investing, and Canada–US banking options. | Branches and online banking; newcomer and account-specific applications. |
 Scotiabank | Major bank | Personal, business and wealth services; StartRight programme for newcomers. | Branch and digital service; newcomer requirements depend on status. |
 Bank of Montreal (BMO) | Major bank | Personal and business accounts, investments, and cross-border options. | Branch and digital channels; confirm the account’s application requirements. |
 Canadian Imperial Bank of Commerce (CIBC) | Major bank | Everyday, business and investment banking; newcomer services. | Branch and online channels; approval depends on the account and applicant. |
 National Bank of Canada | Major bank | Personal, commercial and investment banking; newcomer services. | Branch and online channels; check local branch availability. |
 Tangerine Bank | Digital bank | Personal chequing, savings and guaranteed investment certificates. | Primarily digital; check residence and identity requirements. |
 Simplii Financial | Digital division of CIBC | Personal everyday banking, savings and international money transfers. | Online and telephone service; it is a CIBC division, not a separate bank. |
 EQ Bank | Digital brand of Equitable Bank | Interest-paying personal account, savings products and guaranteed investment certificates. | Personal accounts require Canadian residence, a permanent Canadian address and the local age of majority. |
 Manulife Bank | Bank | Personal banking, savings and mortgage-linked banking products. | Digital services and advisor channels; confirm eligibility for the product. |
 Desjardins | Cooperative financial group | Personal and business banking through its cooperative network, plus savings and investments. | Caisse and digital service; membership and deposit protection depend on the entity. |
What you need to open an account
| Account type | Core information and documents | What can require extra review |
|---|---|---|
| Personal | Identity and address evidence; contact details and tax residence. The bank supplies its accepted-document list. | Foreign residence, overseas documents, remote verification or an account restricted to Canadian residents. |
| Corporate / business | Registration or incorporation documents, directors, authorised signers, business activity and ownership structure. | Foreign owners, multiple entities, source of funds, expected countries and transaction volumes. Individuals owning or controlling 25% or more generally need to be identified. |
| Trust / foundation | Governing deed or constitutional documents, evidence of authority, signers and the people behind the arrangement. | For trusts: trustees, known beneficiaries and settlors. Foreign foundations require the bank to assess the legal entity and control structure. |
| Brokerage / investments | Identity, tax residence, financial circumstances, objectives and investment experience. | The dealer’s permitted client countries, account type and suitability requirements; a bank account alone does not establish brokerage eligibility. |
Details & sources
For a basic personal bank account, Canadian citizenship and a job are not general prerequisites. Federal guidance includes a route using two reliable documents: one showing name and address, the other name and date of birth; a foreign passport may be acceptable. Alternative identity-verification routes also exist.
Nonresidents may be able to open personal accounts, but the bank may require a branch visit. A legal right to a basic account does not make every digital product available to every overseas applicant.
A bank can request further information or decline a particular business relationship. Requirements for trusts, foundations and foreign entities should be confirmed with the institution before documents are commissioned.
Remote opening versus a branch visit
| Situation | What to expect |
|---|---|
| Canadian resident with accepted digital identity evidence | Some personal accounts can be opened online. EQ Bank, for example, requires Canadian residence and a permanent Canadian address. |
| Moving to Canada from abroad | A pre-arrival application or funds-transfer arrangement may still require identity verification or activation after arrival. Confirm when the account becomes fully usable. |
| Nonresident seeking an account from overseas | Do not assume that an online application accepts foreign-resident clients. Ask the bank to confirm residence eligibility and whether an in-person visit is required. |
| Company, trust or foundation | Remote completion depends on structure and signers. RBC’s online business route, for example, is limited to specified sole-proprietor or single-owner/single-signatory arrangements. |
Compare the costs and payment capabilities
| Check | Why it matters |
|---|---|
| Monthly fee and balance waiver | A fee waiver may require maintaining a minimum balance for the whole statement period. Compare that tied-up cash with the fee saved. |
| Included transactions and cash access | Compare bill payments, transfers, cash deposits and use of other banks’ automated teller machines. Business transaction limits can differ sharply from personal accounts. |
| International transfers and currencies | Check both the transfer fee and the exchange-rate spread, plus intermediary fees. Confirm which currencies can be received and held without conversion. |
| Business operations | Check payroll and supplier-payment support, multiple signers, approval permissions and accounting exports. |
| Leaving Canada later | Ask whether the bank and any associated broker will continue the account for your destination country. Digital accounts can have ongoing Canadian-residence conditions. |